Home Blog Page 137

Will air freight exporters face a peak season fee?

0

Due to an expected high volume of air freight by the end of the year, integrators are considering charging additional fees. This is now also being discussed by some cargo airlines. The move is a reaction to the high demand for air transportation versus scarce capacity. In addition, the USA and Canada are considering stiffer rules for shippers whose goods are destined for consignees in North America. We discussed these and other novelties influencing the air freight industry, with Adam Gunnarsson (AG), Vice President Kales Group BV, on the fringes of the recent Seafood Logistics Conference at Oslo Gardermoen Airport.


CFG: Adam, if a shipper fails to send at least 6 shipments within three months into the USA or Canada, they will be excluded from further business. This announcement by the local authorities come up completely unexpectedly about a month ago and caught the air freight industry by surprise. What is the status of this provision today?

AG: Several carriers we talked to, all say the same thing – instructions are not clear, and the content is constantly shifting. The reason why it has come up, has not been disclosed but it is related to security issues. The instructions sent out from various carriers, have been withdrawn, awaiting new instructions from TSA. The original instructions included goods originating from around 50 countries, including all European countries. Since then, the list of countries has been extended but so far not all countries are included. The carriers are referring to IATA for more information.

CFG: How was the step officially justified?

AG: As indicated, it has not been disclosed to this date.

CFG: At the Norwegian Seafood conference, you indicated that some carriers might soon introduce a ‘peak season fee’ because demand is outgrowing capacity, creating major imbalances in air freight. When will it come and what sums are we talking about?

AG: With the peak season starting in September, air cargo demand is expected to remain robust, particularly in high-demand regions like Asia Pacific. However, capacity constraints are already evident, with flights on many routes already fully booked. The market faces potential additional pressure from reduced belly capacity in Q4 – the shift from summer to winter schedule – and the possibility of strikes at U.S. East Coast ports, which could worsen the existing challenges.
So far, we have only heard of peak season fees being introduced by some of the integrators, but not at which level, as of when, and in what shape or form, i.e. fixed fees or flexible and dynamic pricing.

CFG: Turning to e-trade, widely discussed at the Oslo meeting: is the cargo industry amid a new era of e-commerce, which conversely could lead to the downfall of general cargo?

AG: The cargo industry is indeed undergoing a significant transformation due to the rapid growth of e-commerce. However, whether this signals the downfall of general cargo is a more nuanced question. E-commerce is booming, especially following the pandemic, as consumer preferences shifted toward online shopping. The two segments have different characteristics. E-commerce is smaller parcels, faster transit times and more technology-intensive; more frequent shipments rather than large, less frequent general cargo loads. General cargo, which includes large, irregular, or bulky goods, still has a vital role in global trade. Industrial sectors, energy, construction, and manufacturing, rely heavily on general cargo services to ship raw materials and equipment. E-commerce does not serve these sectors well, due to the nature of the products being shipped. The demand for bulk goods, machinery, and large-scale materials in global supply chains, remains substantial. The industry is evolving, and general cargo is likely to persist alongside e-commerce as part of a more diversified logistics landscape. The key for companies will be to adapt — those that can successfully integrate e-commerce logistics with traditional cargo models will be the winners.

CFG: Back to the seafood issue discussed in Oslo: The Norwegian fishing industry and its freight forwarders are complaining about the withdrawal of freighters and the resulting lack of main deck capacity. Doesn’t this development also offer the opportunity to create a greater balance between air freight exports and imports through the shift to e-commerce?

AG: Yes, as long as e-commerce hubs in Europe are spread to more countries and airports. So far, they have been concentrated at a few airports such as Liège, Budapest, Madrid, etc., but we now see airports like Copenhagen and Oslo expanding, attracting more inbound e-commerce volumes. Increasing e-commerce volumes coming into Oslo, will have a positive effect on the capacity balance.

CFG: You said that by 2040, roughly 95% of consumer goods flown by air will consist of e-commerce shipments. Won’t this worsen the current capacity crunch because Airbus and Boeing cannot build a large number of new freighters so quickly and old aircraft are gradually being phased out for reasons of profitability or high CO2 emissions. How will it affect global supply chains if this prediction becomes reality?

AG: I said “95% of all purchases will be done online through e-commerce in 2040.” This statement seems to have come from Nasdaq originally, but has been quoted by Forbes and many other media channels and is today included in facts and statistics of e-commerce. The rapid growth of e-trade will change the air cargo market and spur the need for more capacity. New distribution patterns and supply chains will be required.


Adam, thank you for your insights.
Seafood vs e-Commerce – a battle for air capacities

0

‘The Future of Norwegian Seafood Logistics’ was the headline on the invitation to the event organized by Lars-Gunnar Comen, owner of Swedish exhibition organizer, EuroAvia. However, the big white elephant in the conference room of the Clarion Hotel at Oslo’s Gardermoen Airport, was e-commerce. And for good reason, because Temu, Shein, Alibaba and co., attract air freight capacity like magnets, siphoning it off from traditional air freight flows. This is increasingly affecting the Norwegian seafood business, putting growing pressure on the entire industry, experts confirmed during the event.

Seafood is Norway’s most important industry by far, accounting for 95% of all air freight exports. In 2023, the industry had a total turnover of 14.6 billion euros and produced 2.8 million tons, which corresponds to 39 million meals per day. This is evidenced by data delivered by the state-owned airport operator, Avinor, which manages 32 civil airports in the country, including Oslo Gardermoen, Bergen, Stavanger and Trondheim. Seafood accounts for 55% of all cargo shipments handled at Gardermoen, Norway’s largest airport, said Torgil Stalberg, MD Gardermoen Perishables Center.

Around 90 representatives from the seafood and logistics industry took part in the event organized by EuroAvia owner, Lars-Gunnar Comén  –  photos: CFG/ac

Warning of Bangladesh experience
Panelists repeatedly pointed out that reliable and large freighter capacity is required to transport the temperature-critical shipments from the fjord farms in Norway to the consumer markets as quickly as possible. This worked quite well for years. Recently, however, this is no longer the case, as can be seen from the declining number of freighters serving the Scandinavian country. Airlines have shifted capacity to more lucrative routes, filling them up with e-commerce consignments flown from China to Central Europe, predominantly to Liège, Budapest and Madrid. “Once they have gone, they are unlikely to come back, as the example of Bangladesh shows,” exclaimed Adam Gunnarsson, VP Kales Group. Local manufacturers in Bangladesh are now sitting on their garments because there is too little uplift for textiles due to the shift of capacity to e-commerce. Consequently, Bangladeshi manufacturers are now considering tapping into alternative supply chains via airports in neighboring India.

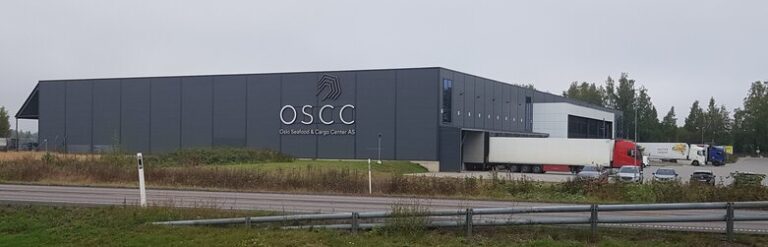
Oslo’s Seafood & Cargo Center offers 46,000 suare meters of cool storage capacity, said Torgil Stalberg, MD Gardermoen Perishable Center AS

More uplift is needed, not less
A warning example for Norwegian shippers and their forwarders because “nothing is in a bigger hurry than a dead salmon,” illustratedOdd-Erik Jenssen, Purchase & Sales Manager Fram Seafood AS, at the Gardermoen logistics conference. “We urgently need more uplift capacity, not only from Oslo, but above all from airports in the north of Norway, where the majority of fish farms are located,” he urged. But how realistic is this wish? Most of the 90 attendees were rather skeptical regarding the fulfillment of this demand, was the general impression at the event. And this despite the fact that seafood accounts for 10% of all commodities flown from Europe to the APAC region and its sub-markets (2023 figure).

Balanced loads required
To make matters worse, the rates on EU-APAC routes have plummeted lately, which doesn’t exactly make fish flights more attractive for cargo carriers. The good news, however, is that the kilo price seems to be leveling out, indirectly due to e-commerce. Stuffed with goods on their westbound flights, the airlines depend on healthy load factors on their way back to the Far East to render the routes profitable. However, Europe is currently experiencing sluggish industrial growth which results in transport imbalances. This is evidenced by 86% inbound freight flown from East Asia to Europe, while in the opposite direction only 45% of the freight capacity is being sold. So, the answer to this imbalance could be a combination of e-commerce inbound and seafood traveling outbound. A win-win situation benefitting all sides: e-traders, the Norwegian fish industry, and Asian consumers of salmon, king crabs, Atlantic mackerel, haddock et alia. Although Europe is still the most important consumer market for seafood (accounting for 37%), China, South Korea, and Japan are catching up fast. For example, 32% of all seafood consignments originating in Norway are meanwhile destined for China.

The Norwegian fish industry is constantly expanding its product mix to further improve its market position

New market considerations
In addition to the seafood vs. e-commerce discussion at the Gardermoen meeting, the question was raised what the industry itself can do better to increase its business. A plausible answer was delivered by Fram Seafood manager, Odd-Erik Jenssen. “We need to expand our product range and offer salmon burgers, salmon hot dogs, poke bowl, and other culinary nuggets based on seafood, in addition to smoked and fresh salmon.” A recommendation that caused many nods of approval.

Exclusive – Globe Air Cargo Bulgaria turns 20!

0

Of all the various players involved in the air cargo industry, it is probably safe to say that the image and role of the traditional GSA has likely changed the most over the past two decades – at least, that of the more successful ones. One such candidate is clearly ECS Group subsidiary, Globe Air Cargo Bulgaria. The GSSA recently celebrated its 20th anniversary with customer, colleagues and partners. CargoForwarder Global (CFG) asked Globe Air Cargo Bulgaria’s Managing Director, Tania Mlechenkova (TM), about the secrets to her company’s success and for a reflection on then and now on the Bulgarian air cargo scene.

(Front, 4th from right) Tania Mlechenkova celebrates with customers, partners, and colleagues. Image: ECS Group

CFG: Congratulations on your 20th anniversary! How does today compare to 20 years ago, when you first started out? What has changed, what has remained the same?

TM: Indeed, I started working for the air industry 25 years ago. From “Flintstone” to the “Jetsons” illustrates to a great extent the changes over the years. At the time when I started, the only way of communication was by phone, fax and telex. I’m sure the young generation doesn’t even know what a fax machine is! And nowadays, we stay connected while flying. The technological and market developments have significantly reshaped the air industry, but still the core process of flying, taking off, landing, navigating has remained fundamentally the same.

CFG: How have you chosen to celebrate 20 years?

TM: We began planning the 20th year celebration last year. This is our way to express gratitude to the airlines we represent, to our customers and business partners. Finding the venue was a bit challenging. We named the event ‘Elegance in Sky’ and the location had to convey the overall idea which might be described as serene, stylish and inviting. The atmosphere had to reflect the sense of exclusivity and refinement.
But it was not just an event celebrating 20 years of GAC Bulgaria. It was also combined with our Group’s long-term sustainability strategy. Young people and talents are the architects of our future, and they are the ones having the potential to go beyond the boundaries. And our goal should be to encourage them in this path. This is how we came to the initiative to make a donation to one of the Bulgarian math teams participating in international competitions.

CFG: What brought you, personally, to air cargo? What do you enjoy about the industry and what would you advise others considering a career in air cargo?

TM: Luck! I graduated in math science and macroeconomics and, as a student, I never imagined working for the air industry. I searched for a summer job and I came across an announcement for a position of customer service agent in a GSA company. The ‘temporary summer job’ turned to be ‘lifetime one’ or at least for the last 25 years. This was love at first sight. As soon as you smell the kerosene, you already know.
For those who want to work in a dynamic field, in a fast-paced environment, who enjoy ticking opportunities, living on a stand-by, who have passion for aviation, technology and global connectivity – the air industry is the right place.

CFG: What is your business credo and what do you feel is the secret of 20-year GAC Bulgaria’s success?

TM: 20 years is a long journey. But for me, the years have passed in a blink of an eye. Still, this is a remarkable achievement. The principles in doing our job and living a life are the same. It’s like solving a math problem – finding a solution by having certain parameters, and if you remember that every problem has at least 2 solutions – then it’s easy.
There is no single formula for success. But if I must summarize it in 2 words: it would have been – Personal Attitude.

CFG: You are a team of 2, correct? How many airlines do you support, what are the main commodities being exported/imported, and what is the balance export/import?

TM: We used to be a team of 2 for the last 5 years. But at some point, the workflow increased so dramatically that we realized only 2 of us is not enough to meet the customers’ and airlines’ needs and expectations. Currently we are 3 ladies in the office, managing all activities.
We represent 9 airlines in total – both online and offline – covering all kind of commodities: textiles, chemicals, pharmaceuticals, machinery and equipment, electricals, fruit and vegetables, biological samples, dangerous goods, banknotes, watches, AOG, etc. The import still has an advantage compared to the export.

CFG: Looking at the GSSA scene in Bulgaria – what has changed here over the past 20 years? What is the trend when it comes to outsourcing, and why do you believe that is?

TM: When GAC entered the Bulgarian market, there were only 2 GSA companies. Over the years, the number increased to 7 and there was room for all of us… until the world started to change due to technologies and digitalization. The traditional GSA concept is no longer valid. And I must say that we, as a Group and GAC Bulgaria in particular, are more than a pure GSA. We cover all cargo activities – from A to Z.
20 years ago, sales and bookings were the core of the GSA business. Nowadays, it’s just the gravity point around which all other strategies are defined – such as capacity and revenue optimization, implementing new technology, and adopting sustainability.
The era of the ‘prêt-à-porter’ in the air industry is over. The meaning of outsourcing today, is to offer expertise. In that respect, ECS Group is not only the pioneer, but also the leader.

CFG: The European Commission predicts that the GDP in Bulgaria is projected to grow by 1.9% in 2024 and 2.9% in 2025, with exports expected to expand robustly after 2024-Q1, in line with the recovery of external demand, and imports are projected to rebound, led by domestic demand. What is your prediction for air cargo over the next couple of years and what do you see happening for GAC Bulgaria?

TM: Air cargo is not an exception and, as such, correlates with that forecast. The expanding of the IT sector can boost Bulgaria’s ability to produce and respectively export more. Same applies to the automobile and pharmaceutical sectors. The Bulgarian market is a competitive one in terms of quality, cost and innovation. This can result only in a positive trend. The short-term forecast for the next 1-2 years, is for moderate growth. Significant growth can be expected in the medium term.
As long as GAC Bulgaria sets the rules, serves as a role model, and supports other companies as they adhere to those rules, the good future is secured.

CFG: How would you evaluate the level of digitalization in air cargo processes in Bulgaria to date? What works well, and what requires improvement?

TM: In Bulgaria, digitalization in air cargo processes is progressing under EU regulations, which encourage digital standardization. The local government is also modernizing the logistics and transport sectors. While many Bulgarian freight forwarders have adopted digital platforms for booking, tracking, and managing shipments, some still use legacy systems and manual processes.
As part of the ECS Group, GAC Bulgaria is fully aligned with the group’s digital strategy, supporting freight forwarders here to embrace these advancements. This alignment helps ensure that our operations and those of our partners stay current with the latest digital trends, maintaining our competitive edge in the industry.

CFG: If air cargo was a Bulgarian dish/food item, which would it be and why?

TM: Banitsa – it’s a traditional Bulgarian pastry made from layers of filo dough filled with a mixture of eggs, cheese and sometimes yogurt. It becomes wonderfully crispy and flaky when baked, contrasting with the soft, creamy filling inside… just like us! [She smiles.]


Thank you, Tania, for this interview!

Forwarders fear e-commerce stampede on general cargo

E-commerce has created a huge upheaval in the air cargo industry. The process may well be unstoppable, creating capacity problems that will also impact general cargo. This is one of the takeaways of a dedicated forum at Liège Airport (LGG), last week.

Ryan Keyrouse, CEO of Rotate – photo: cfg/ms

The venue for the ‘EU Cross-Border e-Commerce Forum’ was well chosen. Last year, Liège Airport handled 330 million e-commerce parcels and for the last 8 months of 2024, over 500 million have already been handled. The cross-border element of this must be seen within the framework of a global place, said Yossi Shoukroun, CEO of Challenge Group, LGG’s oldest customer and main sponsor of the event.

“The winds of change are blowing. This demands excellency, consistency and reliability. The stakes are higher than ever, especially as we are living in a volatile and uncertain world. Air freight and dedicated freighter operations are more crucial than ever. The question is: are we investing enough in infrastructure, technology and people?”

Demand outpaces capacity
According to Ryan Keyrouse, CEO of Rotate, a software and consultancy company focusing on air cargo, a survey with over 50 respondents has revealed that e-commerce is believed to be a key segment, but not yet profitable. Mr. Keyrouse drew attention to seven consecutive months of growth in the air cargo industry of 14%, globally.

This sharply contrasts with the 7% of capacity growth and the 14% growth in demand. “These facts have led to constrained market conditions and growing imbalances, that have increased the gaps in one-way profitability,” he said.

Due to under-reported customs data, the growth of e-commerce is hard to calculate, but estimates show that in China the segment has grown by 22% over the last 2 years, in Europe by 21% and in the U.S. by 23%. For this year, air cargo growth is likely to be another 11% to 12%, and in 2025, 7%. If split up, the latter percentage is made up of 20% growth in e-commerce and only 2% in general cargo.

“This growth could well be unlikely, as capacity is likely to limit the growth in demand,” said Mr. Keyrouse. “Then there are also risks in misdeclaration and political moves.”

Apart from the growth ratio scenario mentioned above, Ryan Keyrouse brought in another scenario of an 8% rise in e-commerce volume and 0% in general cargo, giving an overall growth figure of 2%. “Either way would put the air cargo industry into unchartered territory. The flights on the key trade lanes are always full and the aircraft are in flight almost full-time. Re-deliveries will also add to this limited capacity,” he concluded.

Cannibalizing on general cargo
In the panel discussion on the future of e-commerce, Richard Broekman, Chief Commercial Officer and Head of Sustainability of Atlas Air, seconded the opinion that capacity is the only factor that can limit the growth of e-commerce.

The forwarders, for their part, fear that the growth of e-commerce may cannibalize on general cargo. Asok Kumar, Vice-President Sales and Key Account Management at DB Schenker (Asia Pacific), said that the forwarders too need to know what is happening to e-commerce because it is an important factor in the market. “How do we cater for the traditional segment of the market?” he asked. “How do we support the entire air freight market to be able to grow in a sustainable way?”

800 freighters that will not be there
Air One Aviation’s Chief Commercial Officer, Peter Scholten admitted that the cargo operators are putting all their capacity on the e-commerce market: “e-commerce requires a fleet of 800 freighters, but these 800 are not going to be there in the next few years. This also increases the imbalance.”

Schenker’s Mr. Kumar pointed out that the forwarders have (often long-term) commitments to their customers that they like to respect. “We have secured capacity which can be used to accommodate e-commerce as well.”

This may have an impact on the rates, which will also have consequences, said Stefan Krikken, Head of Airfreight Global DSV: “As air freight becomes more and more expensive, lower-yield goods will shift to other modes.”

Airports and airlines brace for the e-commerce tsunami

0

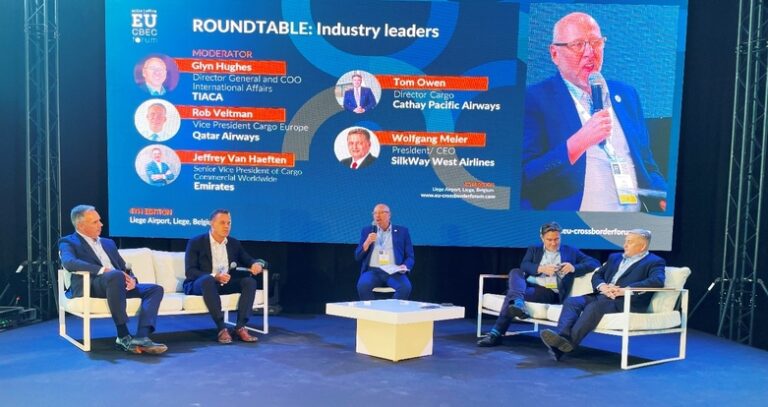
Airlines and airports alike are adapting to the explosive state of affairs of e-commerce, and technology will have to follow suit. That was the leitmotiv of the debate between four airline executives at the Liège e-commerce forum. Glyn Hughes, Director General of TIACA, moderated the session.

Leading airline executives discussed the impact of e-commerce on their operations. Photo: CFG / ms

Full freighter aircraft, high shipment volumes but a gap between capacity demand and transport offer. At the event in Liège, (almost) everything revolved around e-commerce. The segment has become the key growth driver for the air freight industry, particularly on routes between China and Europe. And the boom continues unabated. That was the consensus among the participants as well as the experts in the roundtable discussion.

From caravans to freight planes
Wolfgang Meier, President & CEO of the Azerbaijani cargo carrier Silk Way West Airlines, said his company still has room for growth, as e-commerce currently only accounts for 20% of its total transport volume. The freight airline is building on the relaunch of the Ancient Silk Road, he says. In the past, it was caravans that ensured the exchange of goods between East and West. Today, it is airplanes, but also freight trains and sometimes even trucks. He stressed that Silk Way West is an important partner in the development of the new Baku Airport, an emerging hub in the Caspian region. It will be open to all interested players, once operational.

For Tom Owen, Director of Cargo at Cathay Pacific, e-commerce has been a very pleasant surprise after four difficult, post-Covid years. The segment accounts for 50% to 60% of the company’s volume, compared to 20% to 30% pre-Covid. “This ties into the story of Hong Kong, the largest air cargo hub in the world. If e-commerce hadn’t been around, we wouldn’t have had so many aircraft in service and our fleet would have been younger.”

Jeffrey Van Haeften, Senior Vice President Cargo Commercial Worldwide, stated: “Without e-commerce, the whole industry would have had an issue. Fashion used to be sea freight. Today, new developments triggered by the purchase habits of the younger generation, have brought a change.”

150 full freighters a day needed
Rob Veltman, VP Cargo Europe at Qatar Airways, declared: “We are using the opportunities that the market is offering by adapting our network. We moved capacity to the area where these goods are produced. The top 4 players in the e-commerce industry need 150 full freighters a day and are even looking at sea/air solutions.”

Jeffrey Van Haeften added: “In India, the production has gone up. We are in the perfect storm: while the ocean mode is disrupted, e-commerce is not connected to sea freight. Add to this that B2C is booming and that new products are being launched. Our planes are already full. Delays in aircraft deliveries are a fundamental problem.”

Pearl River
The Pearl River Bay remains the main area of provenance of e-commerce products and not just in Guangzhou only anymore, said Tom Owen. “Dongguan is gaining in importance and the 55-km-long bridge tunnel connecting Hong Kong, Macau, and the mainland offers sea/air opportunities, as well. Hong Kong Airport is expanding its capacity to around 10 million tons annually.”

Emirates is already operating from both Dubai airports, said Mr Van Haeften. “At Dubai International, ground operations are hampered by the heat. Most of the transport will have to be done underground, but there are 5 runways to consider.”

In Qatar, too, the facilities are getting too small, and Qatar Airways is also expanding its fleet.

Artificial Intelligence can support data flow
Parallel to the physical operation, there is also the data flow, with customers needing integrity and seamless data, said Mr Owen. “Four to five leading data services providers are working on a ‘ONE Record’ technology.” According to Wolfgang Meier, there are great opportunities in Artificial Intelligence. “For maintenance planning, amongst others. We are only just at the start of this.”

Yet, the progress in the use of technology takes a different pace in different parts of the world, so it appears. “The European legacy is that they do not like change very much,” thinks Mr Veltman. And according to Jeffrey Van Haeften, the availability of blue-collar workers will also become an issue. “But AI can do the planning,” he hopes.

At the end of the day, the discrepancy between the vibrant business of e-commerce and bureaucracy – like the legislation the EC is working on – may be growing, Mr. Meier fears. “On the other hand, our business is like water. It is always finding its way.”

DSV – Schenker – Mission accomplished

Danish logistics heavyweight, DSV has acquired DB Schenker from parent Deutsche Bahn, in a transaction worth EUR 14.3 billion. Including expected interest income until closing in Q2, 2025, the total sales value amounts to EUR 14.8 billion. CargoForwarder Global already reported on the upcoming takeover of DB Schenker on Friday 13SEP24.

DSV continues its successful acquisition policy. DB Schenker now becomes part of the Group  –  company courtesy.

Following the takeover, the world’s largest logistics company will emerge, well ahead of Kuehne+Nagel and DHL. This applies to all divisions – air and ocean freight, road transportation and solutions.

The outcome of the bidding process was completely open until the current decision. Financial investor CVC, the remaining competitor, offered financial conditions similar to those presented by DSV. It also offered the German state or Deutsche Bahn to retain 24.9% in Schenker. In the event of an IPO at a later stage, this part could then be sold with a billion euro increase in value, the capital investor reasoned.

Politicians forced Deutsche Bahn to sell Schenker
However, Deutsche Bahn and above all the Ministry of Transport headed by Volker Wissing (Liberals) have awarded the contract to DSV. The loss-making railway company, troubled by a dilapidated infrastructure resulting in a lack of punctuality and repeated technical disruptions, was urged by Berlin’s government coalition (Social Democrats, Greens, Liberals) to sell Schenker in order to concentrate on its core business – rail transportation – and reduce its debt burden of EUR 30+ billion. However, Schenker is the only division within DB earning money. “You can only sell silverware once,” commented a source.

As the new 100% owner, DSV plans to invest nearly one billion euros in Germany over the next three to five years. Various central business functions will stay there, including Schenker’s decision center in Essen, North Rhine-Westphalia. The investments will contribute to long-term growth and job creation, as well as promoting modern and attractive workplaces, DSV states in a release. Its management anticipates that in five years from now, the combined organization will have more employees in Germany than Schenker and DSV have today. All Schenker jobs will be maintained for a period of two years after completion of the transaction. Combined, both companies have 147,000 headcounts worldwide. They generate annual sales of EUR 39.3 billion (2023).

Schenker’s name will vanish in 2027 – latest
Until the closing of the transaction, DSV and Schenker remain two separate companies conducting their businesses as they have done so far. At the same time, both management boards are working on the integration of Schenker into DSV, because of which Schenker will lose its name, ending 152 years of proud company history.

On the occasion of the takeover announcement, Jens H. Lund, Group CEO, DSV stated: “This is a transformative event in DSV’s history, and we are very excited to join forces with Schenker. With the acquisition, we bring together two strong companies, creating a world-leading transport and logistics powerhouse that will benefit our employees, customers and shareholders.”

The executive went on to say: “By adding Schenker’s competencies and expertise to our existing network, we improve our competitiveness across all three divisions: Air & Sea, Road, and Solutions. […]. The acquisition will provide our customers with even higher service levels, innovative and seamless solutions, and flexibility to their supply chains.”

Jochen Thewes, CEO, Schenker replied to this: “DB Schenker is one of the most powerful and innovative teams in transportation and logistics with more than 150 years of experience. The recent years have been the most successful in our company’s history and we have proven that DB Schenker is fit for the future. We are excited about the future prospects of the combined business. Together with DSV, our goal is to transform the industry and build a truly global market leader with joint European roots for the best of our employees and our customers.”

Panalpina is a cautionary example
Future-oriented and positive statements such as those made by Thewes are common in company mergers. Their primary purpose is to avoid creating job fears among employees. However, it remains to be seen whether Thewes and Schenker’s top management will still be sitting on their chairs after the two-year peace period has expired.

Market experts point to Panalpina, where thousands of Panalpina employees lost their jobs once DSV took over the Swiss forwarding agent on 01APR19. “Our company was completely gutted in a short period of time,” a former Panalpina executive told CargoForwarder Global. This happened despite an integration committee with equal DSV and Panalpina representation having been set up to ensure the fair treatment of all employees. In retrospect, its setting up proved to be a sop to Panalpina shareholders to facilitate the takeover of the Swiss logistics company by DSV without much fanfare.

History sometimes repeats itself
Many positions will initially be formally filled twice once integration gains momentum. Then it will soon become clear who stays and who must go, despite all the vows to work together as partners and make consensus-oriented decisions to embark on a bright future.

It remains to be seen whether the DSV-Schenker deal will trigger a new round of mergers. Competitors such as DHL, Kuehne+Nagel, Sinotrans or Nippon Express will probably try to increase their market power not only by growing organically, but also through acquisitions. They might also win Schenker customers Schenker who switch to other logistics service providers because they oppose the DSV takeover deal.

Commentary: DSV-Schenker takeover – one winner, many losers

As reported, logistics company DSV is to take over Deutsche Bahn subsidiary DB Schenker. This calls for a comment.

“We would like to thank the German government and Deutsche Bahn for choosing financial investor CVC as our future majority shareholder. This way, the traditional Schenker name will be preserved, and our 72,000 jobs worldwide are secure, as there are no duplicate structures and therefore no reason for major redundancies.”

Schenker boss, Jochen Thewes would probably have spoken these sentences in one way or another if CVC rather than DSV had won the tender for Schenker. As known since Friday, things have turned out differently.

From the Danish logistics company’s point of view, the takeover of Schenker is like a marriage made in heaven. In terms of size, turnover and number of employees, the companies are very similar. DSV thus catapults itself to the top of the global logistics players. The 1976-incepted Danish firm has achieved this pole position primarily through acquisitions, as shown by the incorporation of DFDS Dan Transport, Frans Maas, UTI Worldwide, ABX LOGISTICS, Panalpina, Agility GIL and now DB Schenker. There is no question that the Danes’ aggressive business strategy has proven its worth.

On the other hand, that of Deutsche Bahn has not. DB wanted to become an international big player with Schenker as its global flagship. After the sale to DSV, the Deutsche Bahn Group will concentrate on its core business – rail transportation. However, this is ailing and has been generating high losses for years. The EUR 14.3 billion that Deutsche Bahn will receive from the Schenker sale, will remain within the Group and will be used to reduce debt. This amounts to around EUR 33 billion. So, a debt gap of approximately EUR 19 billion will be left following the sale of Schenker.

As reported by CFG on various occasions, Schenker was the only division of the Group that generated considerable profits year in, year out. These will soon be flowing into DSV’s coffers. DB therefore lacks the funds to brighten up its disastrous balance sheet. Currently, the best-kept secret at DB’s Berlin headquarters is how the managers want to lead the Group out of the red. There is reason to fear that they have no strategy for a financial U-turn at all.

Come 2027, the Schenker flags will only be found in museums – photo: CFG/hs

The second loser alongside Deutsche Bahn, is the German government. It was the tripartite coalition that pushed for the sale of Schenker. Reducing the rail group’s debt was their political credo; especially that of its smallest member, the Free Democrats (Liberals). This is an ideological policy without any economically viable perspective. Deprived of the Schenker profits, the rail company’s deficits will continue to rise. This conclusion is obvious, based on the miserable operating performance of DB, combined with blatantly wrong and costly management decisions and an ailing infrastructure which has been cut to the bone by its owner, the Federal Republic, for more than two decades.

The third loser is Germany as a former top logistics performer. With the imminent demise of Schenker, the country is losing an industrial gem that ranks fourth among the world’s leading logistics service providers. It can be expected that many of the approximately 72,000 employees will quit, as DSV will not allow costly duplicate structures. The Copenhagen-based conglomerate is not known for handing out expensive gifts.

The Schenker sale has not yet been finalized. It still needs the approval of the Supervisory Board. However, the voices of the trade unions, the political opposition, employees and a growing number of customers who oppose the DSV deal, are already getting louder. It is not likely, but cannot be completely ruled out, that Schenker boss, Thewes will be giving a new speech.

Spotlight on… Ryan Colaco, Commercial Director, Coyne Airways FZCO

0

CargoForwarder Global’s ‘Spotlight On…’ series looks at the many different roles that constitute a functioning air cargo industry. Air freight would not happen without the right aircraft and experts who know what works best for which business on which routes. This week, Ryan Coleco (RC), Commercial Director at Coyne Airways illustrates his responsibilities, why he came to the industry, and what his advice is to those potentially looking to join air cargo.

Air cargo is essential – especially during emergencies. Image: Ryan Colaco

CFG: What is your current function and company? And what are your responsibilities?

RC: I am the Commercial Director with Coyne Airways in Dubai. We offer scheduled services into Iraq, Afghanistan, Georgia, Armenia, and over 40 destinations in Africa. We are also a charter broker, specializing in moving time-bound and sensitive cargo to hard-to-reach places. My primary focus is to find the best combination of pricing and transit time for our clients’ particular requirements, and to make sure that we deliver operationally.

CFG: What does a normal day look like for you?

RC: A normal day would typically start with checking the latest news updates and then touching base with clients to follow up on pending requests and with operations to check that everything is on track. The latter part of the day is a bit of a mixed bag as it could involve visits to clients, planning flights, data analysis or renegotiating costs with vendors and service providers.

CFG: How long have you been in the air cargo industry, and what brought you to it?

RC: I have been in the aviation industry for over 17 years, and in air cargo for almost 13 years now.

What made me pivot from the passenger side towards air cargo was a fascination with the global impact of the industry. A lot of the destinations that we serve are landlocked and have little passenger traffic and air cargo is a crucial link in connecting those countries to the global supply chain and providing a multiplier effect for the local economy.

CFG: What do you enjoy most about your job?

RC: Tackling complex operational and logistical challenges, and the satisfaction of seeing projects through to completion.

CFG: What do you see the greatest challenges in our industry?

RC: The biggest short-term challenge I foresee right now is with capacity this peak season. eCommerce is driving a lot of demand, but there are moves from regulators to look more closely at shipments and ensure that there is full compliance. It will be interesting to see how that plays out over the next few months.

Long-term, sustainability is a huge issue, and the race is on to make sure that we are all doing what we can to meet the needs of the present without jeopardizing future generations’ ability to do the same.

CFG: What advice would you give to people to get into the air cargo industry? Any particular training they should aim for?

RC: I would say to look for an organization where you have the opportunity to learn as many things as possible in a way that works for you. Generally, in aviation, you have to choose between large companies with formal training programs where you may only learn a small part in a big industry, and smaller companies where you may get hands-on experience with a broader range of responsibilities and skills. Some of it will come down to how best you learn and where you are in your career journey and confidence. I would also seek out mentors and peers, wherever possible.

CFG: If the air cargo industry were a film/book, what would its title be?

RC: “Aerial Arteries”: the air cargo industry has always been essential, especially during emergency situations.

Thank you for your answers, Ryan.

If you would like to share your personal air cargo story with our CargoForwarder Global readers, feel free to send your answers to the above questions to cargoforwarderglobal@kopfpilot.at We look forward to shining a spotlight on your job area, views, and experiences.

DHL Express goes all in for peak season 2024

0

DHL Express ramps up its investment, increases its shipping capacity and deploys eight additional Boeing B777 freighter aircraft. These steps are being taken by the integrator in preparation of the assumed demand surge for express services in Q4, mainly propelled by fast rising e-commerce volumes.

DHL Express adds 8 B777F to its fleet, this way upping its capacity – company courtesy.  

The buyers of e-commerce shipments expect fast transportation and delivery services according to the motto: ordered yesterday, received today. Parcel delivery companies must meet this expectation, otherwise they risk losing business.

DHL points out that, with an expected increase of 8.8% in 2024, worldwide e-commerce remains a driving force for volume growth, while B2B shipment volume is gradually recovering. Most volumes travel on intercontinental lanes between Asia Pacific, Europe, and the Americas.

Large investment
In reaction to the integrator’s market considerations, DHL Express is investing over EUR 100 million in transport and handling capacity in the fourth quarter, to support its customers’ growth. Flanked by the ongoing modernization of its air freight fleet, DHL Express announced that it will be deploying eight Boeing 777 freighters. Three of these aircraft are newbuilds, while five will be leased long-term on ACMI conditions. The freighters will be based in Leipzig. If Boeing does not meet the agreed delivery deadline for the three freighters in the fourth quarter, DHL will charter capacity on the market to fill the gap in demand, a UK-based DHL spokesman told CargoForwarder Global.

“DHL Express is committed to remaining the partner of choice during the busy end-of-year peak season, which is often the most commercially important and operationally challenging time for many of our customers,” says John Pearson, CEO at DHL Express. “With ongoing volatility in global freight markets and a continued strong flow of e-commerce volumes, we are expecting a healthy surge in demand for express services in the fourth quarter. We are making the necessary investments to maximize the resilience of our global network and make our customers successful during a demanding 2024 peak.”

Many measures help to reduce CO² emissions
Alongside the above-mentioned investments in capacity and ground infrastructure, DHL Express stresses that it remains focused on its longer-term commitment to provide emission-reduced delivery services. In addition to efforts in replacing its global aircraft fleet and designing new buildings as carbon-neutral facilities, DHL Express was the first global express courier to give customers the opportunity to reduce their greenhouse gas (CHG) emissions using DHL GoGreen Plus Services, states a press release. Through cooperation with partners such as World Energy and Neste, SAF (Sustainable Aviation Fuel) is used proportionately in the DHL Express aircraft fleet to reduce CO² emissions. Based on the ‘book and claim’ approach, the reductions achieved (Scope 3) are passed on to customers in the form of certificates. The integrator points out that current challenges like geopolitical tensions and trade barriers have led to the need for reorganizing supply chains, but they have not restricted the air freight sector’s inherent dynamism.

Gemini partners announce first targets

0

The name says it all. Like twins, the ocean giants, Maersk and Hapag-Lloyd, intend to closely interlink their global transport capacities. The starting signal will be given on 01FEB25, but preparations are already in full swing at the companies’ headquarters in Copenhagen and Hamburg. The first focal points of the future cooperation have now been presented.

The Gemini partners have set themselves ambitious goals

The network planners for maritime routes linking the Far East and Europe, are currently working on two options: the passage through the Suez Canal and – as an alternative – the bypass of the African continent currently practiced by both shipping companies for security reasons. Which of the two networks will be given the final go depends on geopolitical rather than operational factors. In a nutshell: should the Houthi rebels stop shelling commercial vessels in the Gulf of Aden, the Suez Canal will be given top sailing priority. However, should the assaults continue, depending on the conflict between Israel and the Houthi-supported Hamas terrorists, the much longer route around the Cape of Good Hope will be retained.

In OCT24, the Gemini partners will disclose their network priority including operational specifics, they state in a joint announcement. Depending on the network decision, between 57-59 services will be offered to the market each month. This includes mainliners and extensive feeder services. In total, they will operate a fleet of 300–340 vessels, ensuring reliable transport capacity.

Improving punctuality is top of the Gemini agenda
In addition to a fine-tuned network structure, Gemini will also focus on the punctuality rate of its transports. “We will raise the bar for schedule reliability […] and set a new and very high standard in the industry,” both carriers promise in a joint release. It is a highly ambitious goal, as these figures illustrate: In JUL24, the Maersk fleet reached a punctuality rate of 54.6% on average – a decrease of 14.9% according to a year-on-year comparison.

Hapag-Lloyd’s performance is even poorer: 48,8% (JUL24) versus 61.7% (JUL23). However, its main competitors did even worse as a chart tabled by Sea Intelligence evidences:

Chart: Liv Almer – Source: Sea-Intelligence

The main reason for the sharp year-on-year decline in punctuality rates, results from the box carriers’ decision to circumvent Africa to avoid Houthi shelling. This results in significantly longer travel times, higher costs and more CO2 emissions.

ZIM and MSC partner
On Monday (09SEP24), the Israeli shipping company, ZIM, announced that it has entered into a new long-term vessel-sharing cooperation with Switzerland-based Mediterranean Shipping Company (MSC), subject to regulatory approvals. The new services, scheduled to be launched in FEB25, are aimed at enhancing ZIM’s port coverage and operational efficiency. During the announcement, ZIM’s CEO, Eli Glickman emphasized ZIM’s focus on sustainability, noting that the shipping line’s LNG-powered vessels will play a key role in the partnership, reducing its environmental impact. The agreement spans three years and includes vessel sharing and slot swap arrangements across six services connecting ports in Asia, the U.S. East Coast, the Gulf, and the Caribbean.